 Retirement Planner Guide
Withdrawal experiments
Working out how much to draw from each account, year after year, is the hardest part of a retirement plan. The withdrawal experiments do it for you: they set every year’s RRSP, TFSA, investment and business withdrawals to meet a goal you choose.
Run an experiment
- Make sure the strategy has a budget. The experiments aim for it, and won’t run without one.
- Right-click the strategy and choose Duplicate strategy, so you keep the original to compare with.
- Click the sparkle button at the right of the settings bar and choose an experiment.
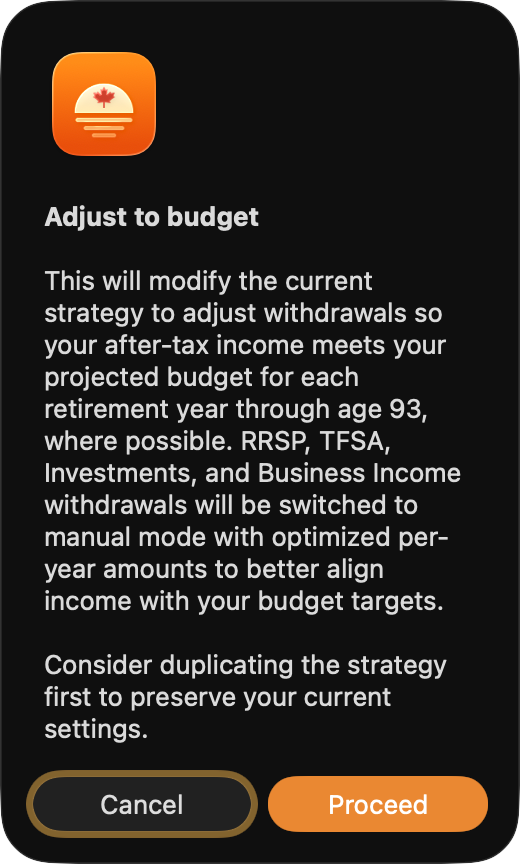
- Read the explanation and click Proceed (or Apply).
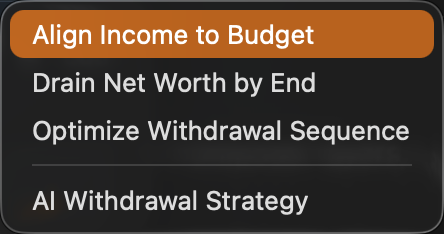
Align Income to Budget and Drain Net Worth by End are also on the strategy’s right-click menu.
An experiment changes the strategy you run it on: the four accounts switch to year-by-year withdrawals with new amounts. There is no undo, which is why it is worth duplicating the strategy first.
Align Income to Budget
Sets withdrawals so that income after tax meets the budget in every retirement year, where the balances allow it. Use it to spend no more than you need, keeping the rest invested.
When it finishes, a summary reports any years still short of the budget or above it, with the average gap, and the net worth left at the planning age.
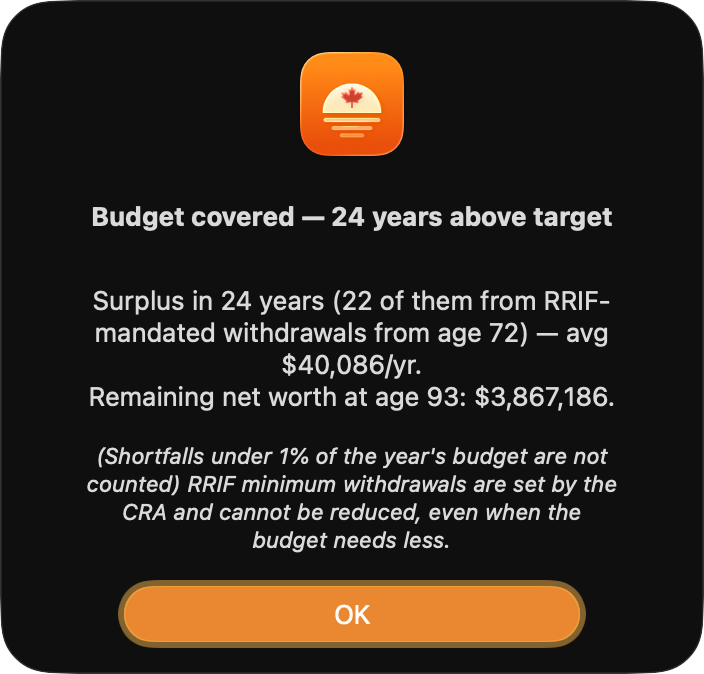
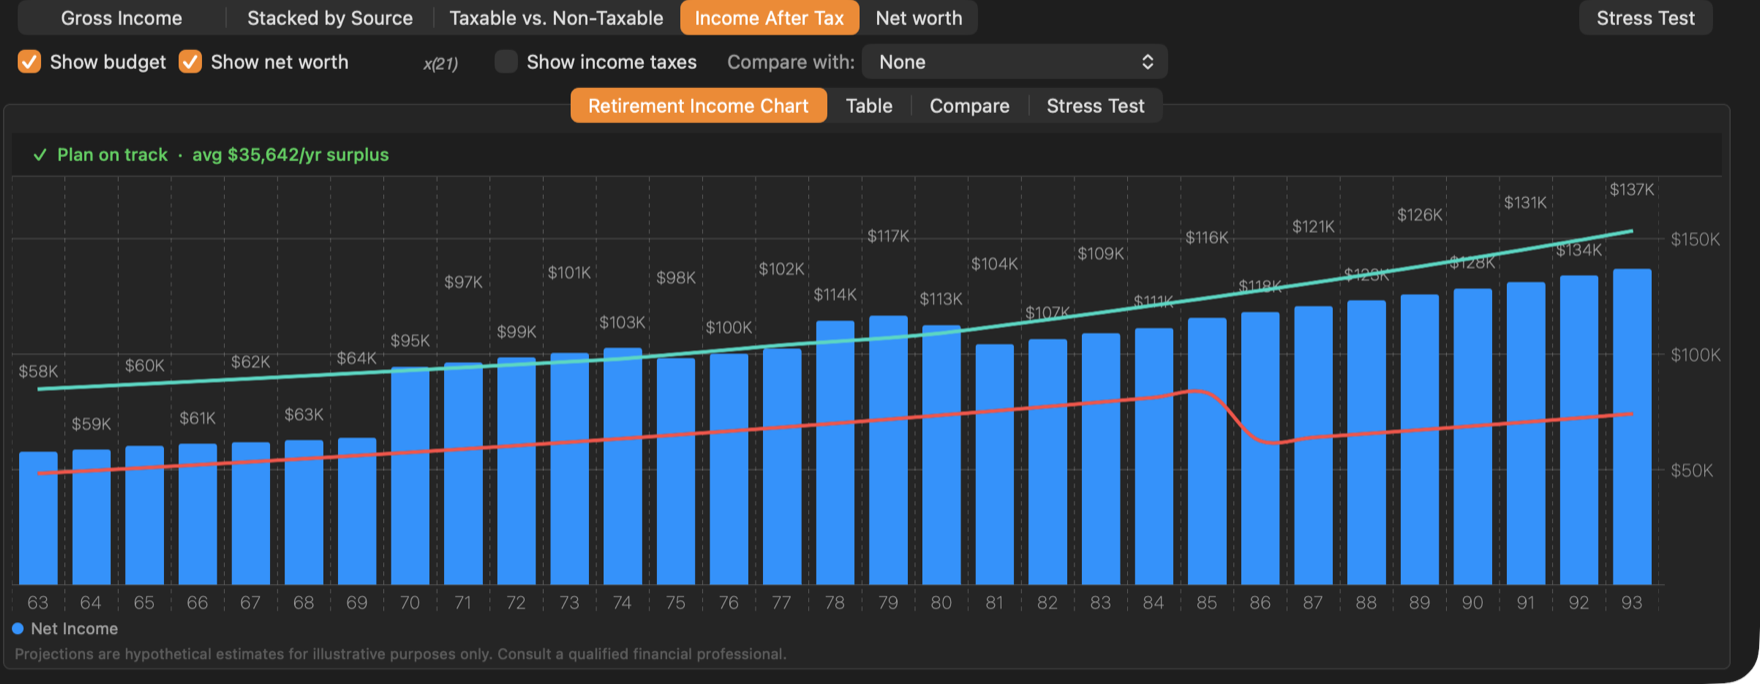
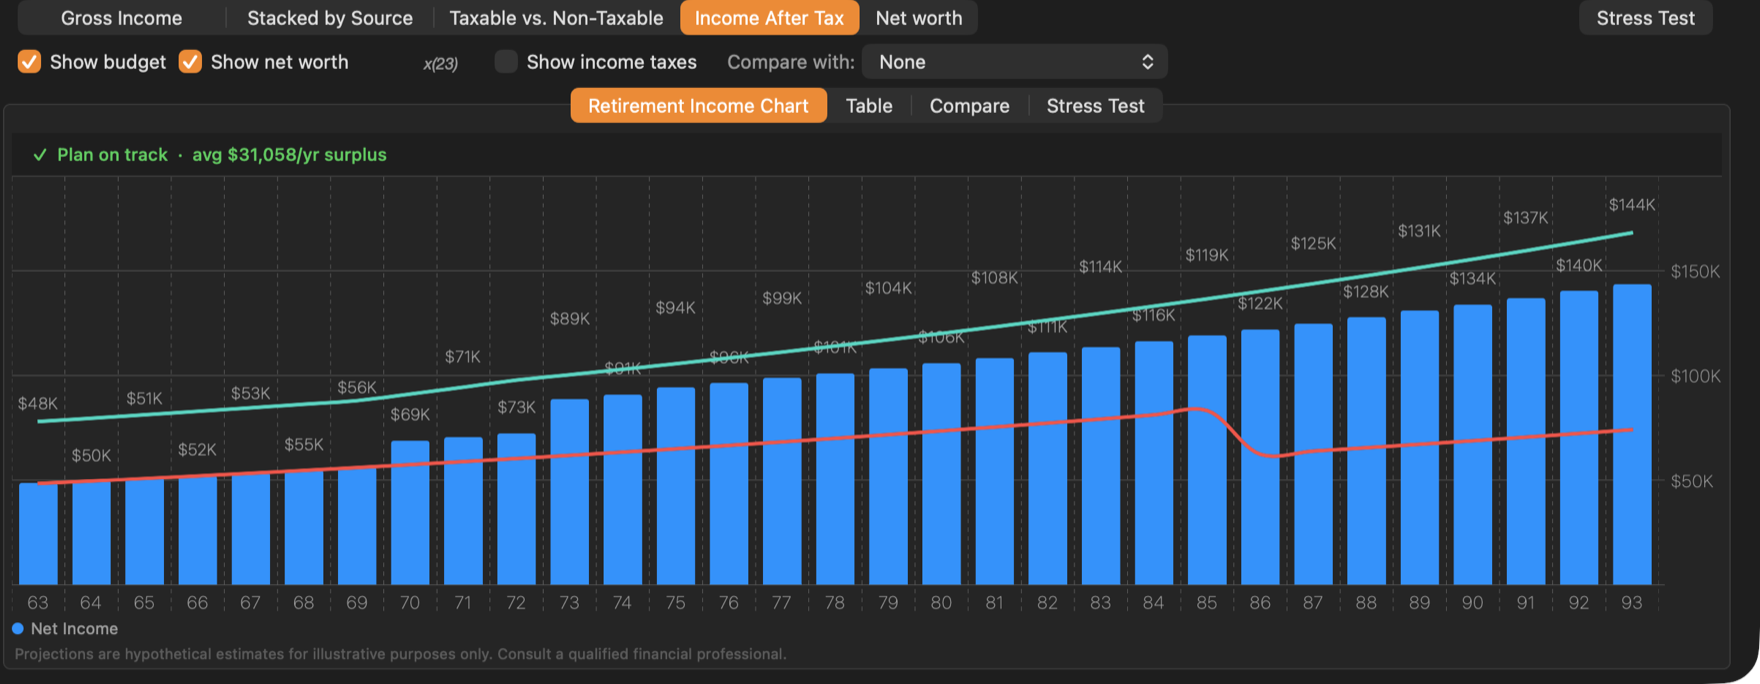
Some years can stay above the budget: from 72 (the default RRIF start age), the RRIF minimum withdrawal may be more than is needed, and pensions, CPP and OAS alone may cover the budget. The summary says how many years that applies to.
Drain Net Worth by End
Spends the savings down so that little is left at the planning age, while keeping income at or above the budget. Use it to see how much more the client could spend — on travel early in retirement, for example — instead of leaving a large estate.
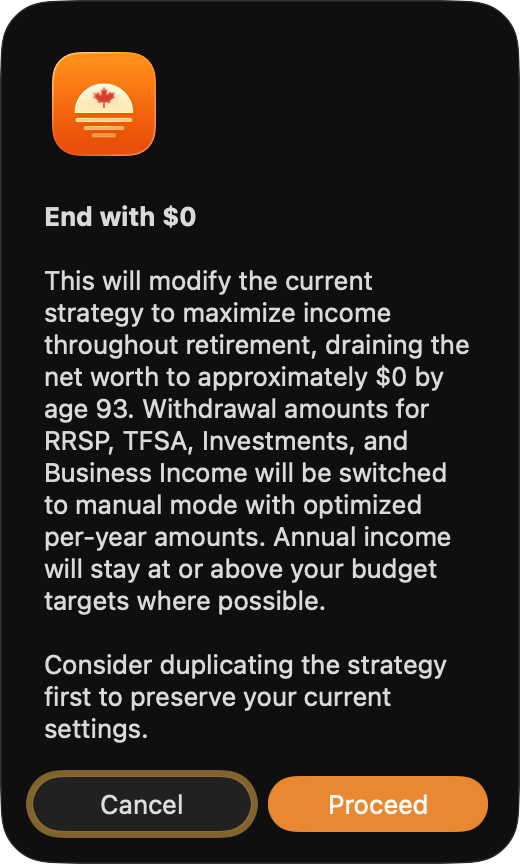
Extra withdrawals go mostly into the early years. The result reports the net worth remaining at the planning age.
Optimize Withdrawal Sequence
Meets each year’s budget while choosing which account to draw from first, to lower the tax. Choose a policy:
- Bracket Smoothing — keeps RRSP and RRIF withdrawals under the OAS clawback threshold, then draws from non-registered investments, the TFSA, and finally more RRSP. Good for large RRSPs that would otherwise cost OAS.
- Conventional — non-registered first, then TFSA, then RRSP: keeps tax-sheltered money growing longest.
- RRSP-First — draws down the RRSP first, to avoid a large tax bill on the RRIF at death.
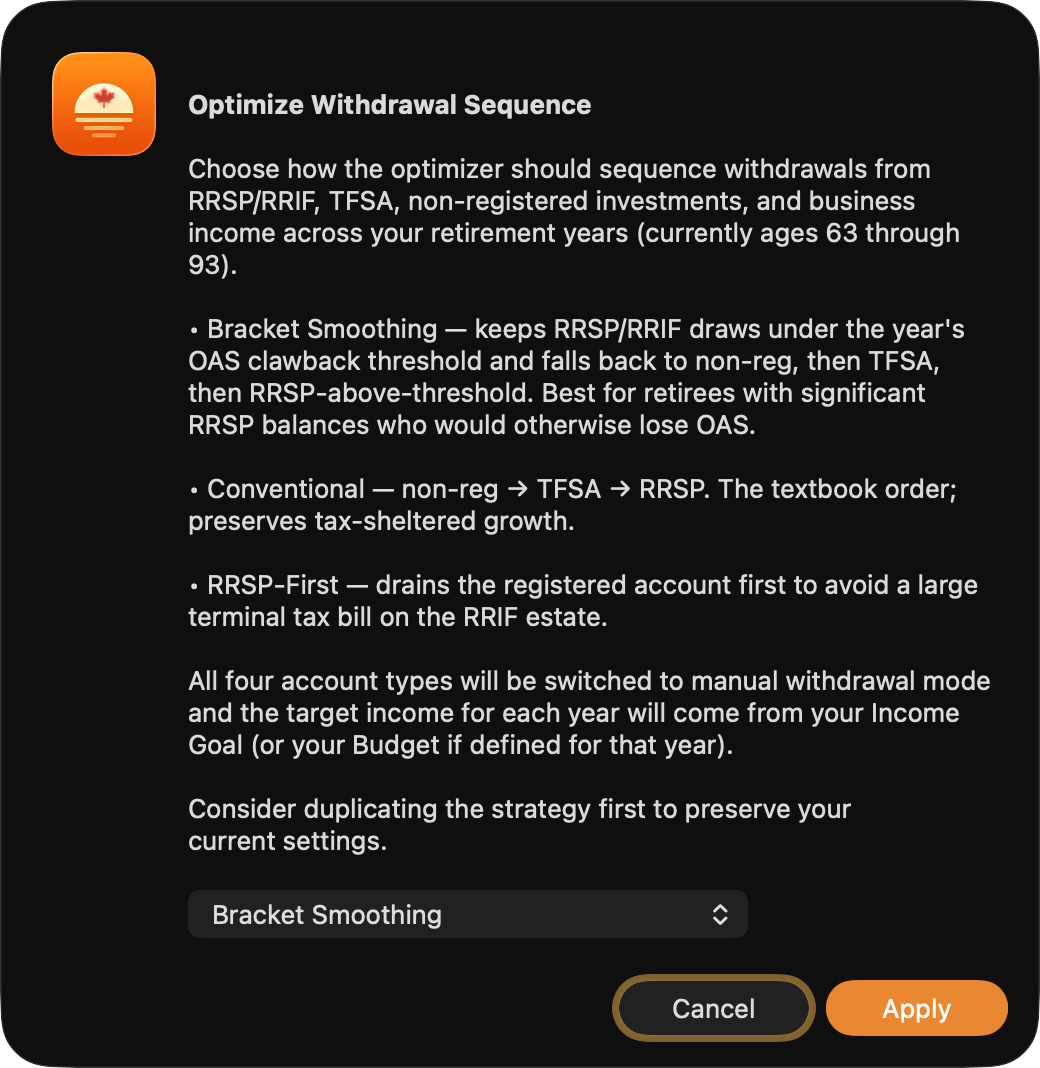
This experiment is only in the sparkle menu. It applies the new withdrawals straight away, without a summary; look at the chart and the RRSP, TFSA and Investments tabs to see the result.
Check the result
- Compare the changed strategy with the original. See Comparing strategies.
- Open the RRSP tab and click Edit ... to see or fine-tune the year-by-year amounts. See Year by year.
- Run a stress test to see how the new plan copes with markets that don’t follow the averages.
For a suggested plan explained in words, see AI withdrawal strategy.